All currency amounts in the illustrative examples below are in USD.
1. Overstating Revenue and Metrics: The Credibility Trap
Many founders, especially in early-stage SaaS, fall into the trap of presenting optimistic or inflated revenue numbers—sometimes by misunderstanding what counts as Monthly Recurring Revenue (MRR) or by including pipeline deals, trial users, or one-off payments. Buyers and investors are quick to spot inconsistencies between claimed metrics and what’s verifiable in Stripe, bank statements, or accounting exports (see Stripe Analytics).
For example, counting an entire annual subscription as one month’s MRR overstates its monthly recurring value. A difference between $5,000 MRR and $3,500 cash collected needs reconciliation: annual billing, invoice timing or past-due balances can explain it without proving an overstatement.
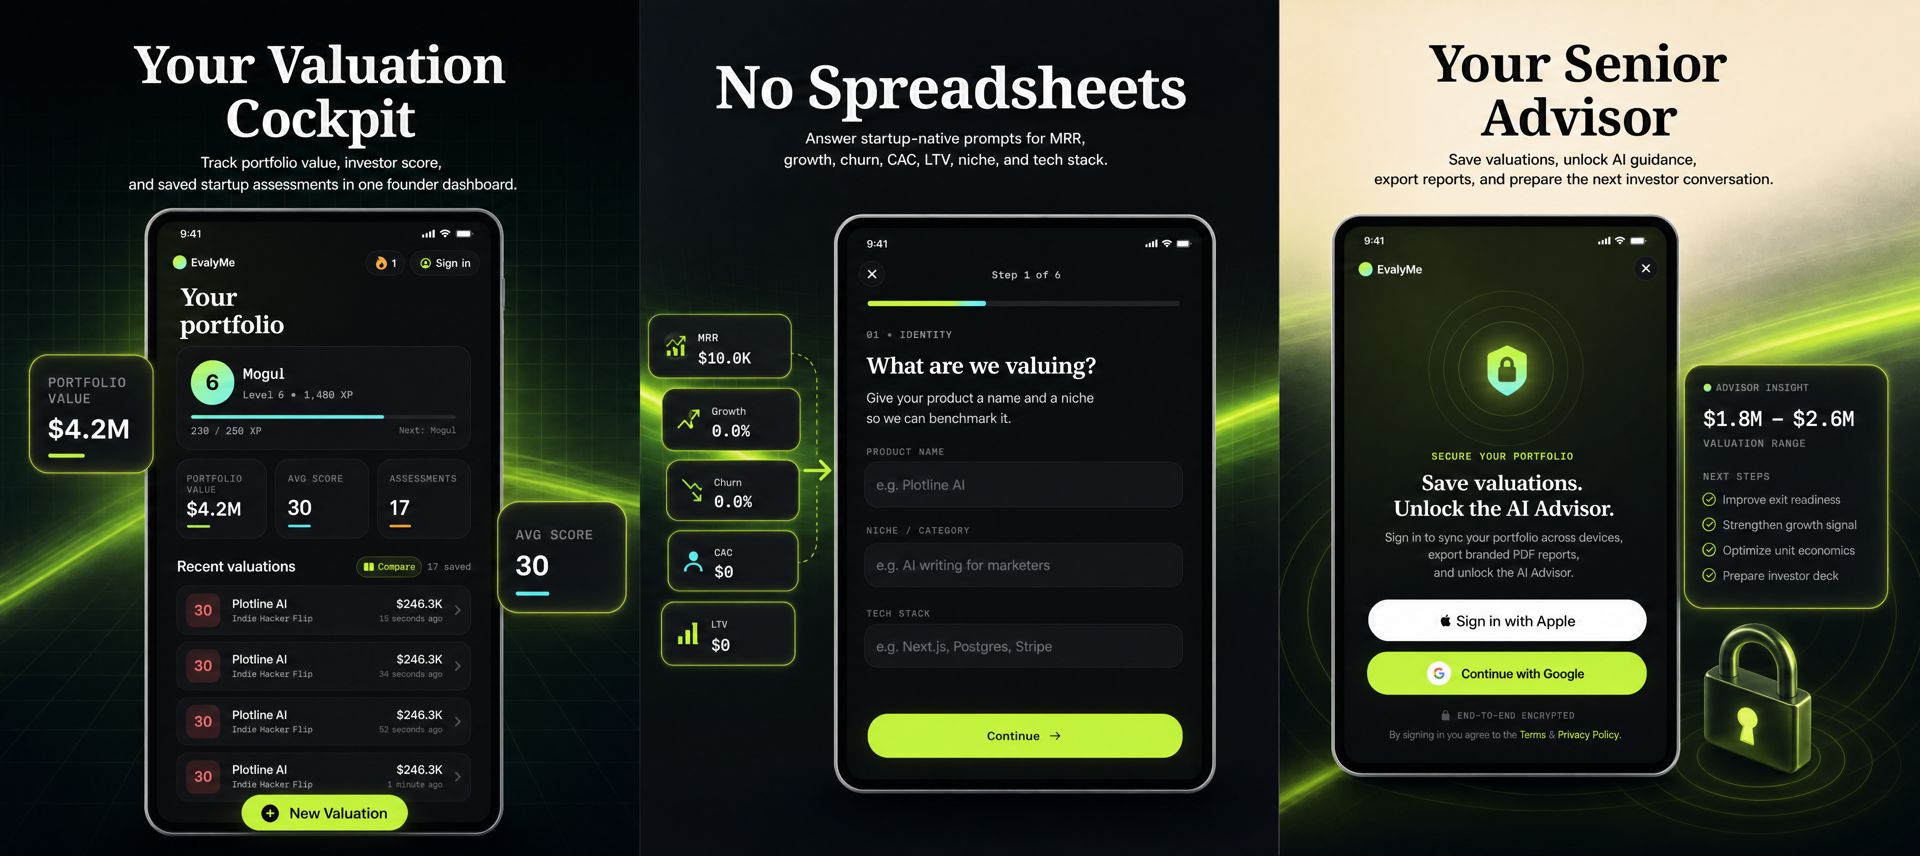
Action: Document your provider’s MRR definition and discount settings. Stripe monthly-normalizes active and past-due subscriptions; canceled and unpaid subscriptions cease contributing. Reconcile collections separately, and exclude pipeline and one-time fees from recurring revenue. See Stripe’s definitions. Use the EvalyMe calculator to compare clearly labelled input scenarios.
2. Ignoring Churn and Retention Signals
Churn is a core risk signal for SaaS buyers. Founders often ignore or understate churn, hoping growth will compensate. However, even modest churn can dramatically reduce a business’s value, since it signals weak product fit, poor customer experience, or unsustainable acquisition tactics (see Why Churn is a Valuation Discount).
Illustrative example: if you lose 10% of starting MRR each month and replace exactly that amount through new and expansion MRR, net MRR stays flat. Distinguish gross additions from net growth so you can explain how much acquisition effort replaces lost revenue.
Action: Track churn monthly using your billing system’s reports. Calculate both gross and net churn. Be ready to explain any spikes or anomalies. Use the calculator’s churn input to see how even small improvements can shift your valuation range.
3. Misunderstanding What a Calculator Estimate Means
A common mistake is treating a browser-based valuation calculator as a guarantee of what buyers will pay. The EvalyMe calculator provides a directional estimate based on your operating metrics—not a formal appraisal, fairness opinion, or offer. It doesn’t ingest private deal data or account for buyer-specific strategic fit (see methodology).
For instance, if the calculator gives a $120,000–$180,000 range for your SaaS, that’s a heuristic based on your inputs and public model assumptions. Real offers may be higher or lower, depending on diligence, negotiation, and buyer fit. Treat the estimate as a planning tool to identify weak signals, not as a price promise.
Action: Use the calculator to pressure-test scenarios—change one input at a time and note what moves the estimate. Prepare to defend your inputs and explain what you’re doing to improve weak areas.
4. Confusing a Working Demo with a Transferable Business
With the rise of AI-built apps and rapid prototyping, many founders mistake a functional demo for a production-ready, transferable business. Buyers want more than code—they want a reliable product, documented processes, and evidence of real users and revenue (see What Ships After the Demo).
For example, a SaaS with $0 revenue but a slick AI demo is not valued the same as one with $1,000 MRR, low churn, and documented handoff procedures. Buyers discount for technical debt, lack of support documentation, or missing compliance.
Action: Before seeking a valuation, ensure your SaaS is production-ready: automate onboarding, document infrastructure, and provide clear support channels. Use the calculator’s maturity and user inputs to see how these factors affect your estimated range.
5. Relying on Market Multiples Without Context
Founders often anchor on headline SaaS multiples from public markets or hearsay, applying them to their own business without context. These multiples rarely apply to small, private, or bootstrapped SaaS, which face different risks and buyer pools (see SaaS Valuation Multiples).
For example, a founder might expect a 6x multiple because they read it online, but their SaaS has high churn, limited growth, or is dependent on a single customer. The real-world outcome is often lower, and buyers will adjust for risk, size, and growth potential.
Action: Use the calculator to see how your own metrics drive the estimate. Focus on improving your operating signals (growth, retention, LTV/CAC) rather than chasing generic multiples.
6. Failing to Document and Justify Key Metrics
Buyers and investors will request evidence for every key metric: MRR, churn, growth, LTV, CAC, and user counts. Failing to document these, or providing inconsistent data, is a red flag. This is especially true for AI-built SaaS, where code and infrastructure may be opaque.
Checklist:
- Export MRR and churn reports from Stripe or your billing provider
- Document customer acquisition costs (ad spend, tools, labor)
- Show how LTV is calculated (average revenue × average lifespan)
- List active users and their engagement
- Provide a timeline of product updates and support tickets
Action: Prepare a data room, even if informal, with exports and explanations. Use the calculator’s input fields as a guide for what buyers will want to see.
7. Overlooking Weaknesses in Unit Economics
Unit economics—especially LTV/CAC—are central to SaaS valuation. Founders sometimes ignore or fudge these numbers, hoping buyers won’t notice. But weak unit economics (e.g., LTV barely exceeding CAC) signal unsustainable growth and high risk.
Illustrative Example: Suppose your SaaS spends $500 to acquire a customer (CAC), and the average customer pays $50/month and stays for 8 months (LTV = $400). Your LTV/CAC is 0.8x—meaning you lose money on each customer. The calculator will flag this as a weak signal, pulling down your estimate.
Action: Audit your acquisition and retention costs. If LTV/CAC is below 1, focus on either reducing CAC (cheaper channels, better targeting) or increasing LTV (upsells, retention). Use the calculator to model improvements and set realistic priorities.
8. Mistaking the Estimate for a Buyer’s Offer
Perhaps the most damaging mistake is believing that any model output—calculator, spreadsheet, or advisor—is equivalent to a buyer’s actual offer. Real-world outcomes depend on negotiation, buyer fit, diligence findings, deal structure, and market timing (see What a SaaS Valuation Calculator Can and Cannot Tell You).
For example, two SaaS businesses with identical MRR can sell for very different prices if one has sticky enterprise customers and the other relies on churn-prone consumers (see Why Two SaaS Businesses With the Same MRR Can Sell for Very Different Prices).
Action: Treat your calculator estimate as a starting point for planning and gap analysis—not as a commitment from a buyer. Use the output to prioritize improvements, but be ready to adapt when real offers and diligence begin.
Ready to pressure-test your SaaS valuation? Use the EvalyMe free SaaS valuation calculator to get a directional range based on your actual inputs. Review the methodology to understand the model’s scope and limits. For a step-by-step exit-readiness plan, see The 90-Day SaaS Exit-Readiness Plan.